THE COMMERCIAL LOAN CHECK
Think commercial finance is too hard to get moving on? Most of what’s stopping you isn’t what you think.
Business premises, an investment property, a shopfront you’re sick of leasing - the finance side feels harder than it is. Answer honestly below and see exactly what’s actually in your way, in about 30 seconds. No obligation.
STEP 1 - WHAT’S ACTUALLY IN YOUR WAY
Tick what’s been holding you back
Pick anything that sounds familiar. Nothing is sent anywhere - this just shows you where you actually stand.
THE COMMERCIAL LOAN CHECK
Click each one that applies. You’ll see straight away whether it actually rules you out - usually, it doesn’t.
0 of those - and none of it takes you out of the game.
Every one of those is something I work through with clients every week. The honest next step isn’t a form that spits out a number - it’s a 15-minute conversation where I tell you straight whether it stacks up, and what it’d actually take.
No problem - let’s just talk it through.
Tell me what you’re looking at and I’ll tell you straight whether it stacks up, and what it’d actually take. About 15 minutes, no obligation.
Ready to find out for sure? Leave your name and mobile and I’ll call you back - no jargon, no obligation.
What are you looking at? (optional, tap one)
Rough price range? (optional, tap one)
Thanks - got it.
I’ll call or text you on within one business day. Rather lock in a time now?
Pick a time that suits you →Or call or text 0403 343 177.
WHAT ACTUALLY CHANGES
What owning instead of leasing actually unlocks
This is the part that doesn’t show up on a spreadsheet.
Your own warehouse, instead of another year of lease
BUSINESS PREMISES, ACTUALLY OWNEDA shopfront that builds equity instead of a landlord’s
RENT MONEY, WORKING FOR YOUThe investment property that pays its own way
COMMERCIAL YIELD, DOING THE HEAVY LIFTINGA fit-out that’s finally worth doing properly
BECAUSE IT’S YOURS TO KEEPRoom to expand without asking a landlord first
YOUR BUILDING, YOUR CALLA retirement plan that isn’t just “sell the business”
BRICKS AND MORTAR, ALONGSIDE ITHOW IT WORKS
Three steps, no paperwork yet
Tick what applies
Work through the list above honestly. Nothing is sent anywhere at this point.
See it’s not what you thought
Almost every objection people carry into commercial finance turns out to be a non-issue with the right lender.
Have the actual conversation
If it’s worth pursuing, we get on a call and I tell you straight what it’d take - no sales pitch, just the real answer.
WHO YOU’D BE TALKING TO
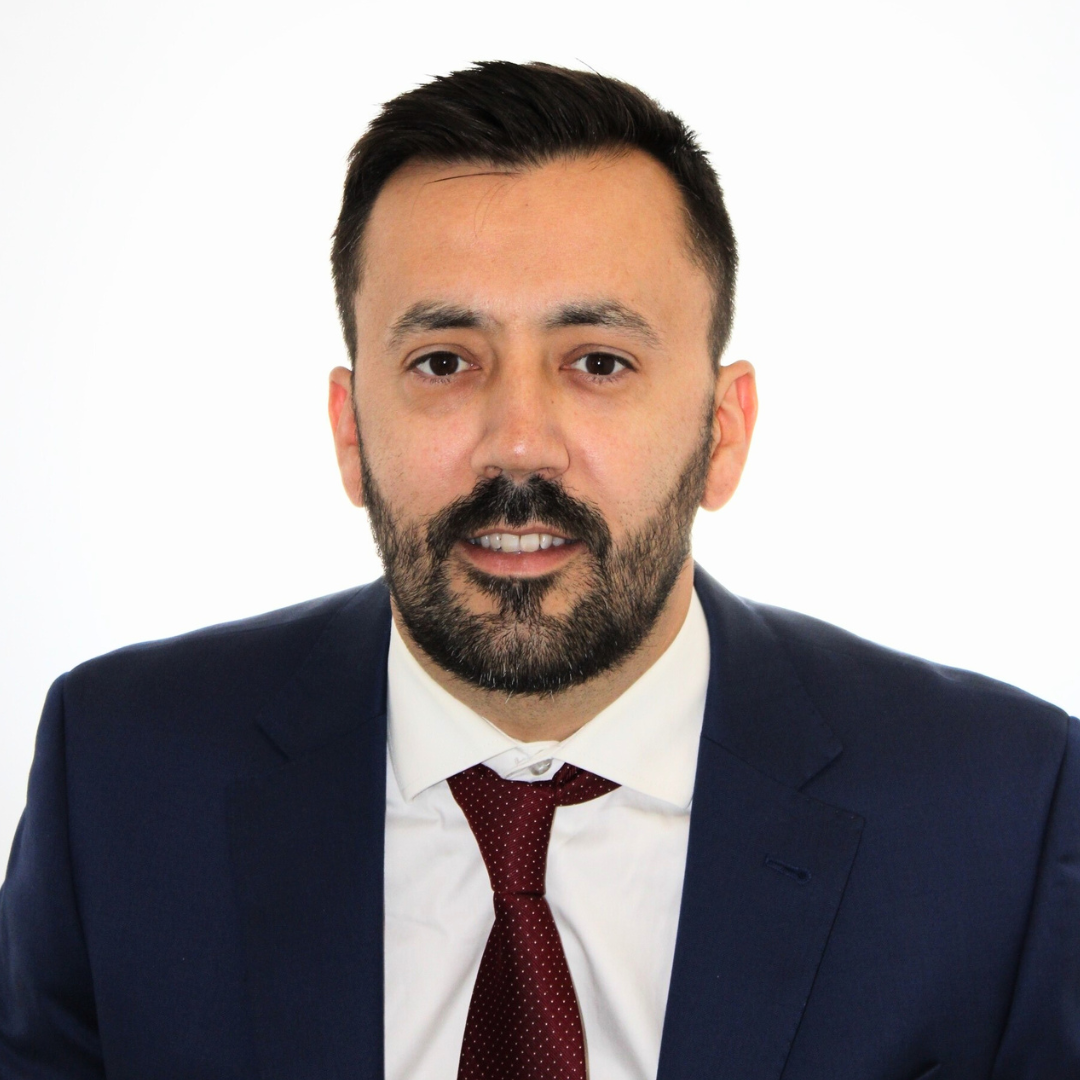
About Dragan
Dragan holds a Bachelor of Finance & Banking (Honours) and a Certificate IV in Finance and Mortgage Broking. He helps business owners and investors finance business premises and commercial property - matching serviceability, security and structure to lenders who understand commercial deals, not just home loans.
★ 5.0 on Google - YBR Inner Melbourne
NO EMAIL NEEDED
Free guides
Download straight away - these don’t require anything above.
Commercial vs Residential Lending, Explained Plainly
What actually changes - LVR, rate, loan term, security - written for business owners, not brokers.
Download PDF ↓Buying Your Business Premises: The Checklist
What to line up before you approach a lender, so a missing document never costs you the deal.
Download PDF ↓Where a Bank Says No and a Specialist Lender Says Yes
Why one credit policy isn’t the whole market, and what changes the answer.
Download PDF ↓STRAIGHT ANSWERS
Common questions
How much deposit do I need for a commercial property?
There’s no single answer. Every lender sets its own maximum LVR, and it moves with the property type, location, lease and your financials. Commercial LVRs are usually lower than for a home, but equity in another property can often make up the difference. The quickest way to know is to match your deal against several lenders.
How long can a commercial loan run for?
Each lender sets its own maximum term, and it’s often shorter than a home loan. Some commercial loans are written for a set period and then reviewed. Lenders also look at your age alongside the term, mostly through your exit plan - how the loan eventually gets repaid.
Do I need two full years of financials?
Not always. Many commercial lenders will work with BAS, an accountant’s declaration or business bank statements instead.
Can I buy through my company, trust or SMSF?
Yes, all three are common. Each changes which lenders fit and how the loan is set up. SMSF borrowing in particular has strict rules, so get advice from your accountant or SMSF adviser on the structure first, and I’ll handle the lending side.
How long does a commercial approval take?
Usually longer than a home loan, mainly because of the commercial valuation. It varies by lender and deal, so talk to me before you sign and allow a realistic finance clause in the contract.
Is a commercial loan more expensive than a home loan?
Usually a bit, and it’s often priced deal by deal rather than off a published rate card. Valuation and establishment fees are typically higher too. I’ll show you the real costs side by side before you decide anything.
Will talking to you affect my credit score?
No. A conversation doesn’t involve a credit check. That only happens if you decide to apply, and only with your consent.
VERIFIED, NOT WRITTEN BY US
5.0 on Google
Real reviews from YBR Inner Melbourne’s listing - see them all on Google Maps.
“From the very beginning, he was professional, responsive, and genuinely took the time to understand our situation and goals. We couldn’t be happier with the result.”Milica Filipovic · Google review
“Always available whenever I needed assistance - even during holidays and weekends. His guidance made the whole experience much smoother and less stressful.”Dragana Radulj · Google review
“Fantastic encounter with my broker Dragan.”Sivagami Mathuray · Google review